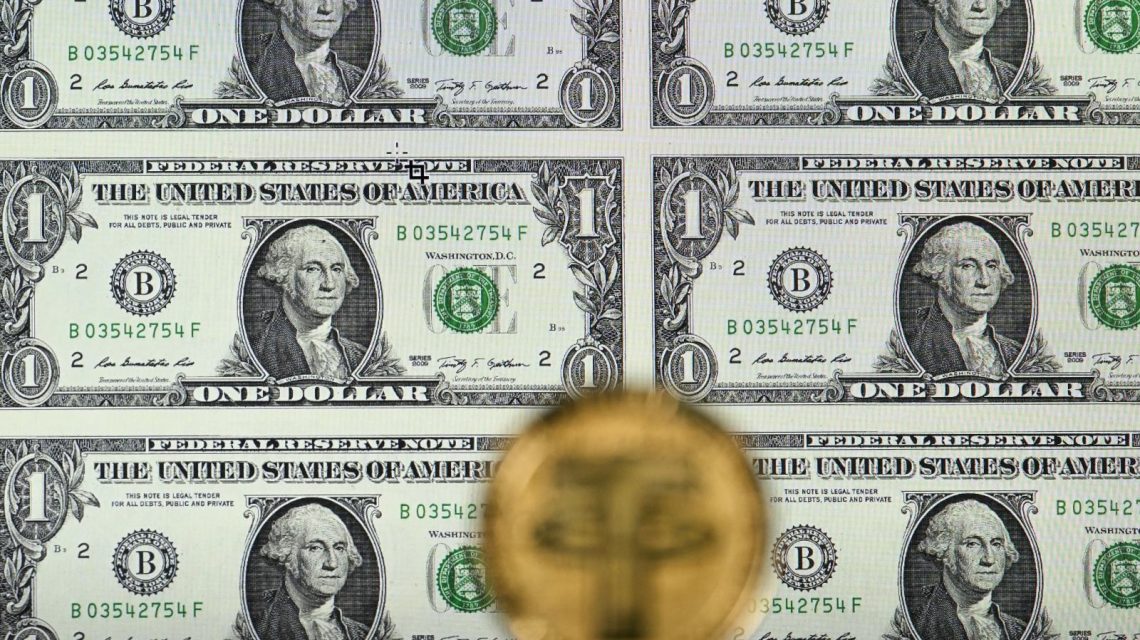
Sending a wire transfer on a Friday afternoon means your money may be stuck until Monday. This is because international payments often involve multiple intermediary banks, each taking a fee and causing delays. Unlike instantaneous text messages, money transfers are slow. Stablecoins appeared to offer a solution to this problem by using digital tokens pegged to the dollar. These tokens move quickly over blockchain networks, settling transactions in seconds.
Stablecoins are gaining solid legal status, attracting the interest of Wall Street. However, the true potential lies not in layering stablecoins onto existing banks, but in creating federally chartered banks built specifically around this technology.
The Plumbing Problem
Understanding how money moves highlights the limitations of current systems. When you send a payment, the money doesn’t physically travel. Instead, banks adjust balances on their ledgers and settle through global messaging networks. These systems, designed decades ago, process transactions slowly and close on weekends.
International payments are even more challenging. Most countries’ banks can’t hold dollars directly and rely on American banks’ accounts. This creates a chain of correspondent banks, each adding fees and delays. Stablecoins avoid these routes, clearing transactions on blockchain networks even late at night or on holidays. They are programmable, allowing automation and conditional payments. As AI starts negotiating payments, this flexibility becomes crucial.
Why Big Banks Can’t Upgrade
Large banks struggle to adopt new technologies because they can’t simply update like software. Their operations rely on outdated infrastructure and interlocking processes. To change money movement methods, banks must overhaul their core technology, treasury operations, compliance, risk management, legal, and audit decisions. Each department wields veto power, resisting the radical changes needed for stablecoin integration. Established tech stacks and global reach often hinder rather than help.
Building a New Type of Bank
A new approach is emerging. Augustus, a startup, received conditional approval from the Office of the Comptroller of the Currency to become a national bank. Shortly after, it raised $180 million. A national bank charter grants direct access to U.S. payment systems and allows holding deposits. Financial technology firms often operate above this layer, partnering with banks and facing limitations. Augustus aims to be a clearing bank with stablecoin infrastructure from the start. It benefits from not having to work around legacy systems or bureaucracy meant for batch processing.
What a Bank Becomes
Technology-native banks can showcase what streamlined financial infrastructure truly looks like. Their potential advantage isn’t blockchain access, which will become common, but their speed and flexibility. A bank like Augustus can launch new products swiftly, similar to a software firm. When new financial innovations arise, they can adapt quickly. Stablecoins will redefine both how money moves and what is expected from a bank’s operations.
Sami Start, the co-founder and CEO of Transak, is involved in providing global Web3 payments infrastructure for seamless fiat-to-crypto and crypto-to-fiat transactions.
 Trump’s 2024 Campaign Targets Young Men Through Cryptocurrency
 How Modern Windows Improve Home Insulation
 State Department Simplifies Passport Process with Online Applications
 Senate Democrats Block Data Center Bill Over Efficiency Concerns
 Future Cities: Ambitious Projects Aiming for Innovation and Sustainability
 High-Profile Hearing and AI Developments: Key Political Moves