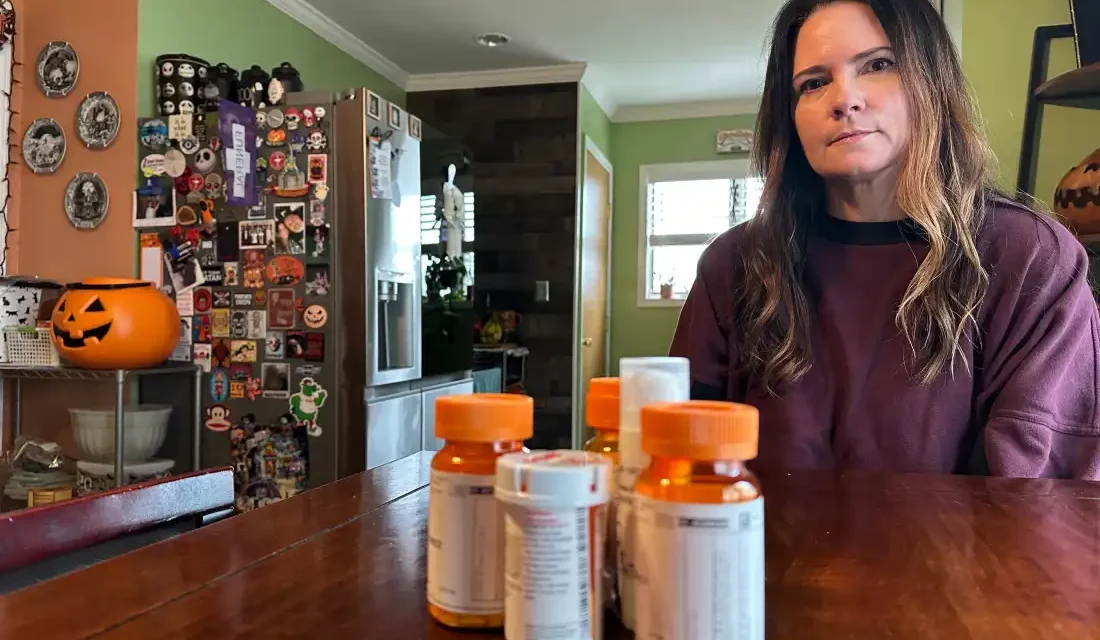
Consumers who purchase Affordable Care Act (ACA) health insurance will encounter both significant and minor changes as open enrollment for 2027 coverage begins. These adjustments include higher premiums, additional identity verifications, potential delays in broker interactions, and revised rules on immigrant subsidies.
Start of Open Enrollment
Open enrollment begins on November 1st in most states. However, states like Idaho, Connecticut, and Massachusetts started earlier. Some states offer “window shopping” to preview premium rates. A decline in overall enrollment is anticipated, mainly due to the expiration of enhanced subsidies at the end of 2025. This led to millions dropping coverage earlier in the year. The Trump administration views the drop as a success in reducing fraud, having canceled nearly 760,000 policies over suspected improper enrollments, though some regained their coverage.
Increased Identity Checks
Shoppers will experience greater scrutiny this enrollment period. Requirements to prevent fraud might slow the process for those using agents. These rules apply only to consumers using agents for enrollment via the federal marketplace, which covers 29 states. State exchanges have different, often more effective, rules against fraud.
To authorize an agent, consumers will receive a one-time confirmation code via text, email, or phone call from private enrollment platforms. Those with outdated contact information must update it first. Consumers considered “high-risk” must verify their identity through a third party. These include first-time applicants, those changing states, or individuals working with a new agent. Those struggling with verification may need to contact Experian or apply directly on healthcare.gov, uploading necessary identification documents.
Change in Broker Availability
CMS has placed a moratorium on new brokers for ACA coverage. Unregistered brokers as of 2026 won’t assist with 2027 enrollments until February. This move follows high compliance issues with new brokers. While some agree on the long-term benefits, it causes short-term chaos, making it harder for smaller brokers to serve clients this year.
Smaller agencies often reduce staff post-enrollment, hiring again later in the year. The moratorium unintentionally benefits larger call centers that maintain large staffs year-round. Agent groups are challenging the directive, with lawsuits filed against the administration.
Rising Costs and Subsides
The end of enhanced subsidies resulted in higher premiums for most ACA users. Although subsidies remain, they are less generous. Double-digit premium hikes will occur, albeit slightly lower than last year’s increase.
Subsidies depend on income, ceasing entirely for households earning more than four times the federal poverty rate. Consumers should actively compare plans annually, avoiding automatic renewals to potentially find better options. Deductibles and other costs should be considered alongside premiums.
Out-of-pocket maximums will rise, and subsidy eligibility for many immigrants is stripped by recent legislation. Only specific groups like green-card holders and certain nationals remain eligible.
For those relying on a broker, it’s crucial to schedule appointments early as fewer brokers might be available.
KFF Health News provides in-depth health journalism and operates under KFF, an independent health policy research organization.
 The Future of MAHA in American Health Politics
 Insulin Cost Caps Gaining Support Amid Rising Prices
 Efforts to Counter Food Assistance Cutbacks in San Diego
 A Personal Journey Through Encephalitis
 Low-Cost Medication May Benefit Stroke Survivors
 The Complex Debate Over Kratom Use in the U.S.