Managing debt can be challenging, especially when it escalates to collections. While serious, collections don’t necessarily signal financial disaster. Understanding the process and your rights can help mitigate stress and manage the situation effectively.
The Impact of Debt Going to Collections
When debt enters collections, communication changes. You start hearing from collection agencies rather than your original lender. Expect more frequent and urgent contact, but know that collectors legally must provide a validation notice. This notice informs you about the debt specifics and allows disputing the claim within 30 days.
“Falling behind on payments isn’t uncommon, especially with high everyday costs.”
Credit can suffer due to unpaid collections. Missed payments lower credit scores, and collection accounts can stay on your report for up to seven years. However, not all agencies report collections so the impact may vary.
Misconceptions About Collections
Being sent to collections doesn’t mean automatic wage garnishment. Collectors need a court judgment to garnish wages for most debts. Ignoring lawsuits can lead to default judgments, escalating consequences.
Legal troubles aren’t inevitable either. You can’t be arrested for unpaid consumer debt. Threats of arrest by collectors are illegal and violate consumer protection laws. Responding appropriately to lawsuits is crucial.
Negotiating with Debt Collectors
Options exist beyond paying the full amount. You can negotiate settlements for less or arrange affordable payment plans. Confirm debt legitimacy and understand settlement terms. Written agreements protect against renewing collection lawsuit time limits.
Legal Protections Against Harassment
Collectors have limits. They can’t call outside 8 a.m. to 9 p.m. without consent, nor can they harass or misrepresent consequences. You can request cessation of communication, although lawful recovery attempts may continue.
Conclusion
Collections pose challenges, but you retain protections and options. Verify debts, understand your rights, and explore potential resolutions. Consulting professionals, negotiating terms, or seeking credit counseling are viable strategies. Making informed choices helps mitigate financial stress.
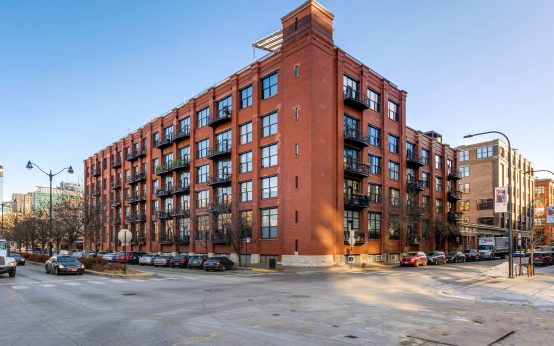 Norma Kuhling Sells West Side Loft for Asking Price
 Two-Story Tiny Home with Modern Features Available on Amazon
 Kirk Cousins’ Off-Market Home Sale: A Real Estate Insight
 Foreclosures and Tighter Credit Highlight Issues with Price Controls
 Office Market Faces Renewed Challenges Amid High Bond Yields
 Raising Children in the Hamptons with Practical Life Lessons