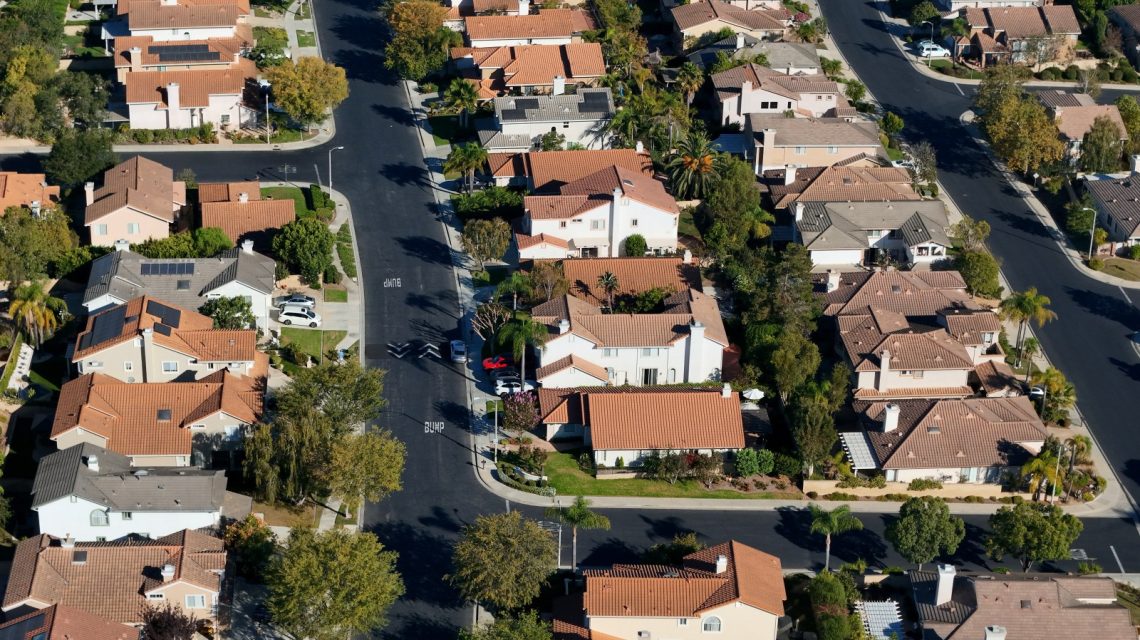
Americans are increasingly choosing riskier home loans with lower rates as they navigate a challenging and expensive housing market. The latest data from the Mortgage Bankers Association (MBA) shows that 8 percent of borrowers opted for adjustable-rate mortgages (ARMs) last week, marking the highest level in five weeks.
MBA’s Weekly Mortgage Applications Survey (WMAS) for the week ending August 28 highlighted this trend. Mike Fratantoni, MBA’s senior vice president and chief economist, stated that ARMs provide an interest rate fixed for a set period, up to ten years, before adjusting periodically based on market benchmarks or lender-set percentages. Though these loans offer short-term convenience, they carry more risk than fixed-rate mortgages due to potential future rate increases.
“Americans’ demand for riskier loans reflects eagerness to buy despite affordability constraints,” said Joel Berner, senior economist at Realtor.com.
Mortgage rates have climbed from just below 6 percent to 6.71 percent since the war in Iran began in late February, further complicating affordability. This modest rate increase can significantly impact monthly payments for buyers with limited budgets, according to Berner.
The national 30-year fixed-rate mortgage averaged 6.71 percent as of the week ending September 3, according to Freddie Mac, with a 0.21 percentage point rise over the previous year. The 15-year fixed-rate mortgage averaged 6.04 percent, up 0.44 percentage points from the previous year.
Home prices also continue to rise. Redfin reports the national median sale price of homes reached $407,730 in July, up 3.2 percent from a year earlier.
ARMs are gaining interest amid lackluster demand for conventional mortgages. MBA noted total mortgage application volume increased just 0.8 percent last week compared to the previous week.
“ARMs make sense for buyers not planning to stay long-term,” Berner explained.
With lower initial interest rates than traditional 30-year fixed mortgages, ARMs offer lower monthly payments during the fixed-rate period. The risk arises when the rate resets and may increase.
For buyers planning to sell, relocate, or refinance before the adjustment period ends, this risk might be avoided. They benefit from the low introductory rate without necessarily facing later higher rates.
Potential for Housing Market Challenges?
Berner acknowledges the risk of mortgage rates moving unfavorably for ARMed buyers, but emphasizes buyers today aren’t exhibiting lower creditworthiness. This contrasts with the subprime mortgage crisis. The demand for risky loans shows buyers attempting to maximize purchasing power amidst higher rates and inflation.
The U.S. market remains “cold,” exacerbated by long-term affordability challenges and economic uncertainty due to Middle East conflict.
“A cool market differs from a crashing market,” Berner emphasized. A crash is unlikely this year.
Even if there’s fluctuating concern, experts agree on minimal risk of involuntary selling or inability to absorb new inventory.
While ARMs offer advantages, risks persist. Rate increases after purchasing an ARM could lead to individual delinquency if new monthly payments become unmanageable. However, widespread impact leading to a broader market or economic crash is viewed as unlikely.
 Navigating Los Angeles Real Estate on a Budget
 Mortgage Rates Return Above 7% After Twenty Months
 Inland Empire Grapples with Growing Housing Affordability Concerns
 Challenges in Los Angeles’ Multifamily Housing Market
 Jevon Carter Sells Chicago Town Home
 Charming River Forest Home With Custom Features