Federal student loan borrowers have faced significant adjustments recently, ranging from the end of pandemic-era payment pauses to the introduction of new repayment programs and changing forgiveness regulations. As borrowers acclimate to these new repayment routines, another round of federal student loan changes is set to take effect on July 1. These changes could affect millions of student loan borrowers by altering their available options.
Assess Your Current Repayment Plan
A critical step for borrowers is identifying their current repayment plan. Many borrowers are enrolled in income-driven repayment (IDR) plans, and some may not have reviewed their status lately. It’s vital to understand where you stand amid changing repayment options and enrollment pathways.
Visit your loan servicer account to verify your repayment plan, discover your monthly payment amount, and determine any upcoming recertification requirements. Compare alternatives to see if switching plans could lower your costs or better align with your goals.
Will You Qualify for Your Desired Plan?
With eligibility requirements changing for some federal repayment plans, it’s wise to consider enrolling before July 1. The deadline could mean fewer pathways into certain repayment programs afterward. Analyze your income, loan type, and eligibility now to maintain flexibility and prevent limited future choices.
Impact on Your Monthly Budget
Student loan payments affect your overall budget, alongside housing, credit card bills, insurance, and other expenses. Evaluate how potential changes may impact your finances. Determine if your budget can absorb any increases comfortably, or if adjustments are needed.
Analyzing your budget preemptively enables you to avoid unwanted surprises and potentially redirect savings toward other priorities if your costs decrease.
Long-Term Repayment Goals
The changes in July offer a chance to reassess your broader repayment aims. Your ideal strategy depends on your objectives, whether it’s paying off debt quickly or pursuing loan forgiveness while managing monthly payments.
For example, if your goal is to eliminate debt rapidly, minimizing monthly payments might not suit you. Conversely, if you’re targeting loan forgiveness, you may prioritize different factors.
“Federal student loan changes on July 1 could alter repayment options significantly. Taking action now can enhance your ability to navigate this transition effectively.”
Review your current plan, confirm eligibility, assess budget impacts, and revisit long-term aims to strategically handle these changes and make informed decisions about your student debt.
 Democratic Governors Face Pressure on Federal School Choice Program
 Navigating School Year Challenges and ‘The Talk’ on Safety
 Former Cornell Instructor Discusses Sexual Harassment Allegations
 Cornell University’s Sexual Assault Allegations Spark Legal Battles and Investigations
 Larkin High School Unveils First Outdoor Sports Stadium
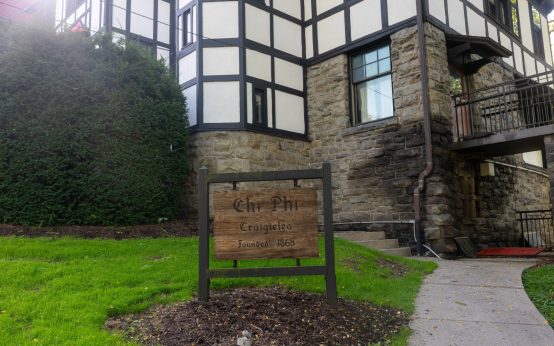
 Cornell University Fraternity Faces Allegations in Sexual Assault Case